Mortgage Lending Powered the Top Line
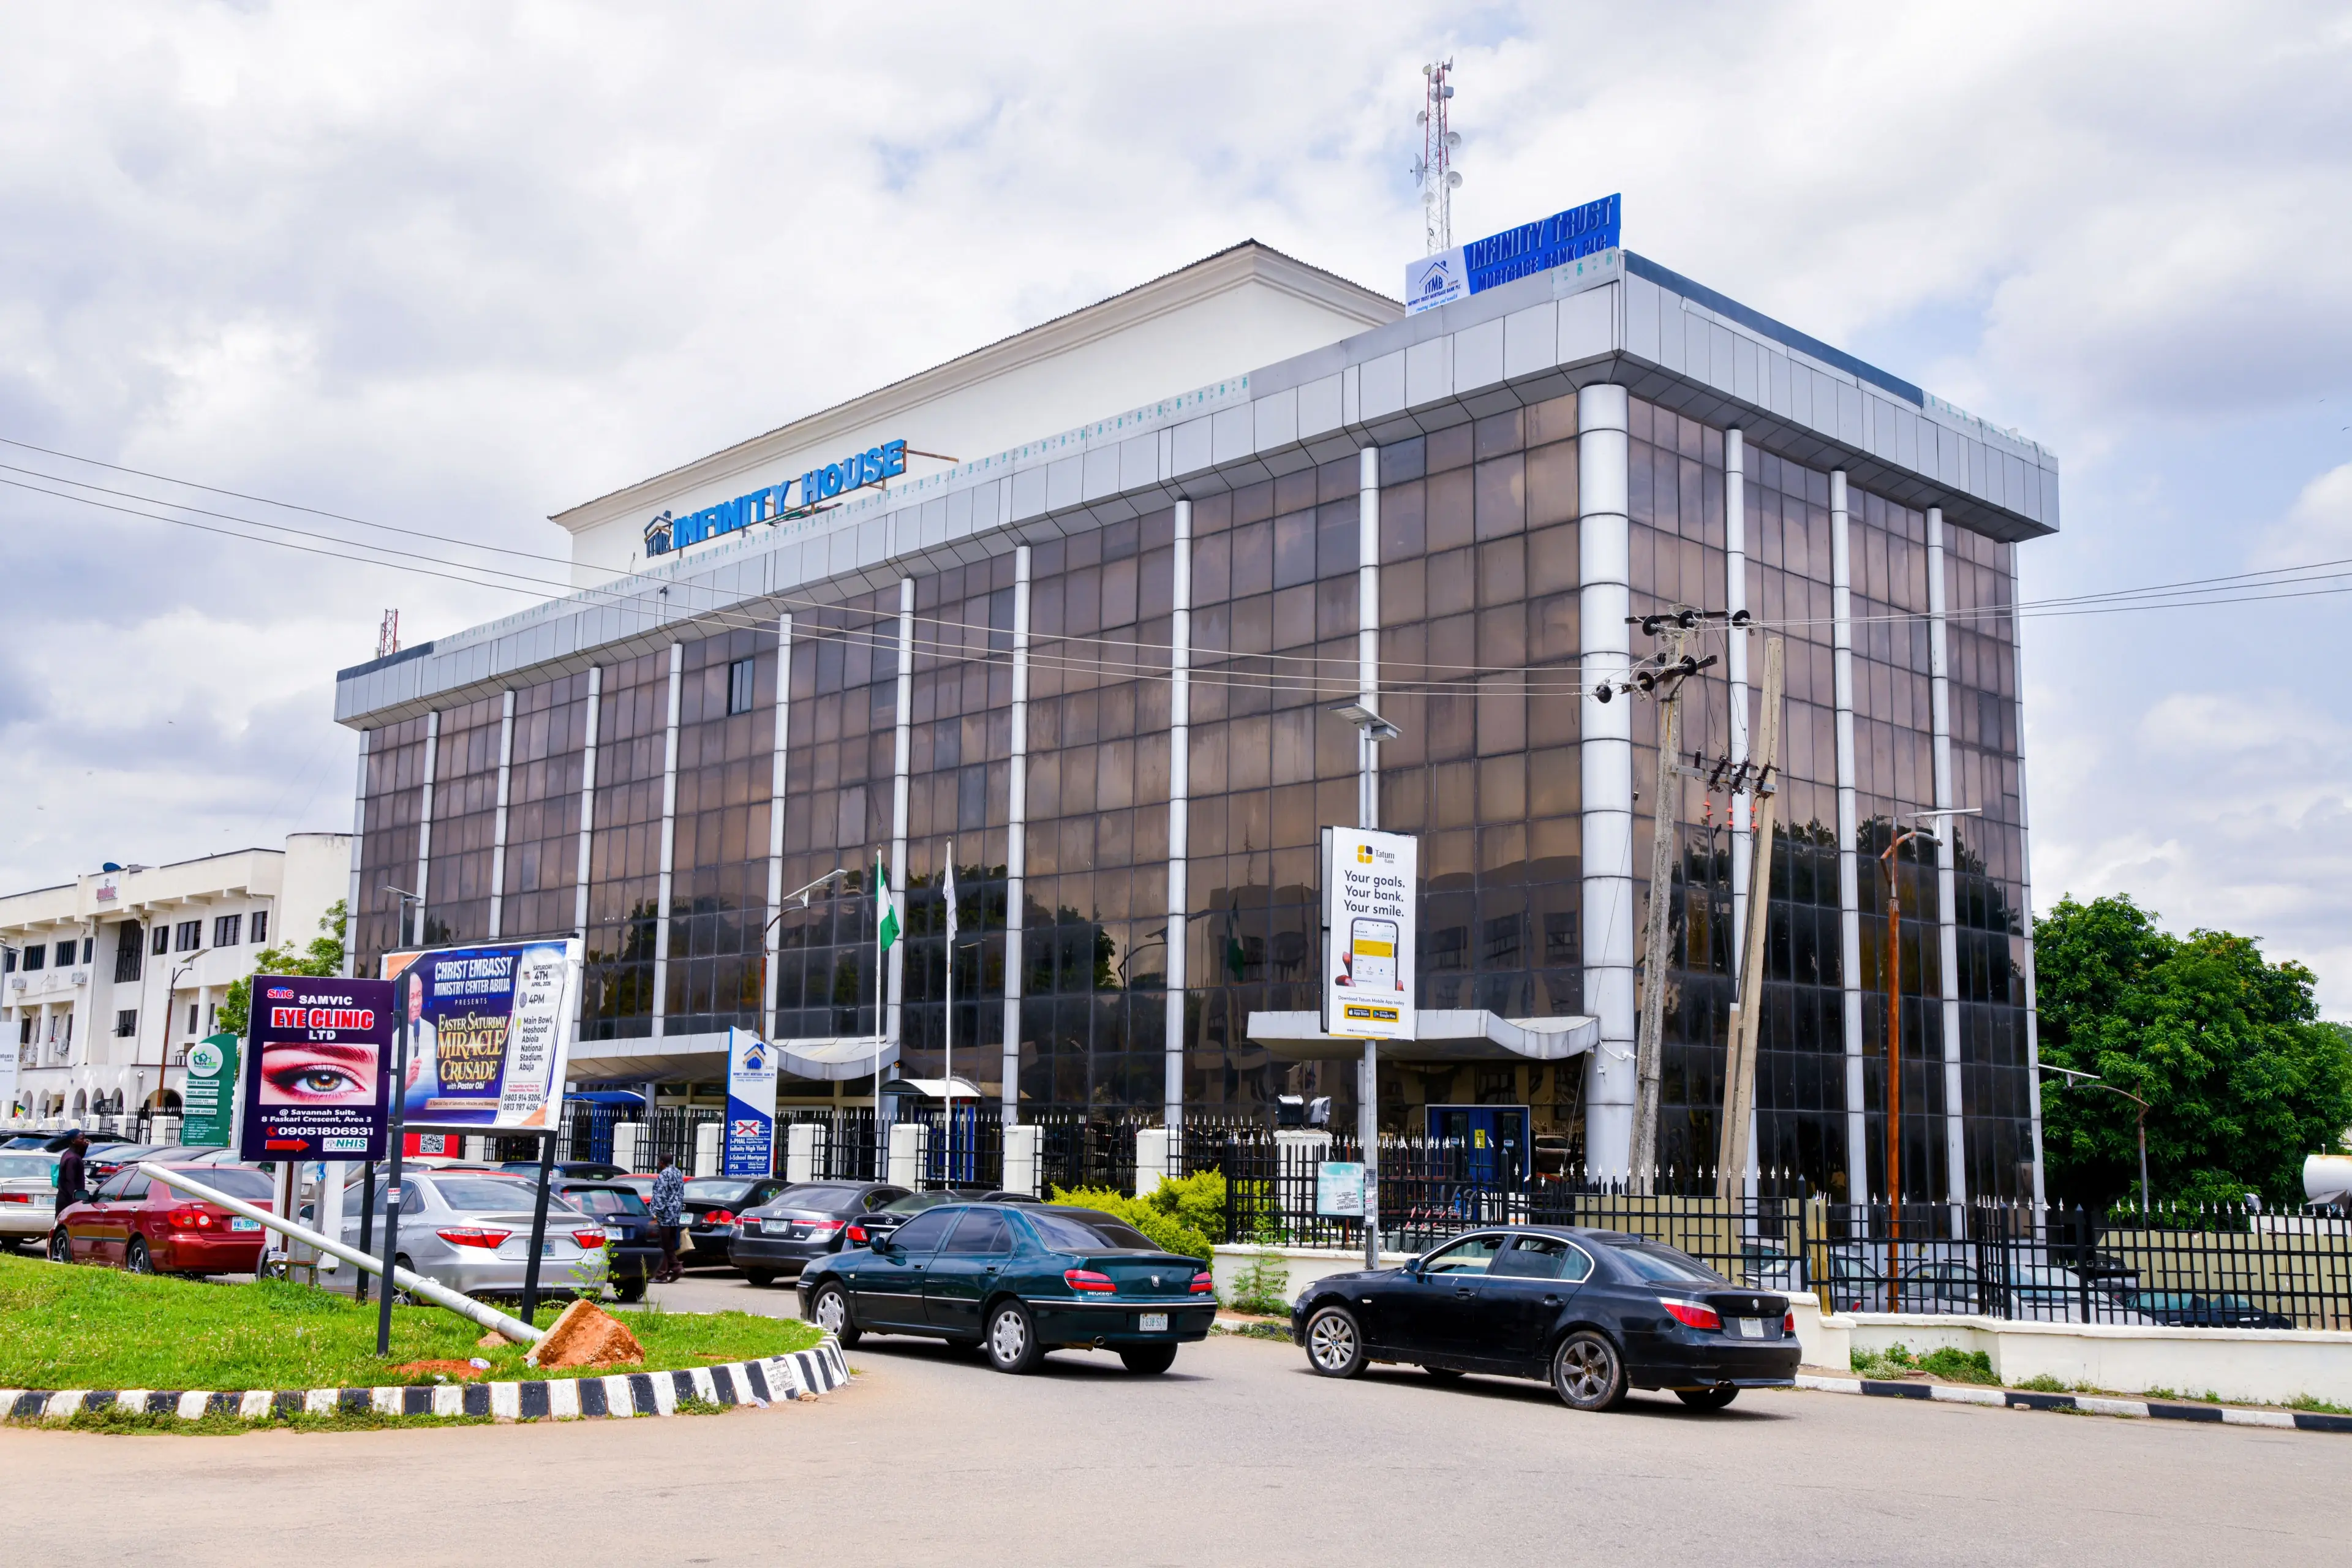
The Abuja-based mortgage lender's nine-month numbers are, above all, a lending-growth story. Interest income from other mortgage loans and advances climbed to ₦4.16 billion from ₦2.57 billion, estate mortgage income rose to ₦565.51 million from ₦335.51 million, and income from treasury operations and placements increased to ₦1.07 billion from ₦787.60 million. Together, those lines pushed turnover up by more than two-fifths.
The loan book tells the same story from the balance-sheet side. Loans and advances to customers grew 46.5% to ₦36.69 billion from ₦25.05 billion, making lending by far the bank's largest asset category, while total assets rose to ₦54.87 billion from ₦37.93 billion a year earlier.
Funding Costs Rose Faster Than Income
Growth did not come cheaply. Interest expenses increased 78.2% to ₦2.19 billion from ₦1.23 billion, with interest on debt and other borrowed funds more than doubling to ₦1.53 billion from ₦651.63 million. As a result, net interest income grew 43.5% to ₦3.70 billion — strong, but slower than the 54.7% expansion in gross interest income.
The funding mix shifted with it. Debt issued and other borrowed funds climbed 87.8% to ₦26.87 billion from ₦14.31 billion, while customer deposits rose more modestly to ₦11.20 billion from ₦9.75 billion. Total operating income still increased 28.1% to ₦4.30 billion, enough to carry profit before tax to ₦2.76 billion.
Cash flow remains the trade-off investors have to weigh. Cash generated from operations was negative ₦5.80 billion, deeper than the negative ₦4.47 billion recorded a year earlier, as new lending consumed cash. Fresh borrowings of ₦7.99 billion helped offset that outflow and lifted cash and cash equivalents by ₦2.71 billion to ₦10.72 billion at the end of the period.
What It Means for Investors
Infinity Trust is compounding earnings at a pace few listed lenders match — the shares trade at ₦11.25 with a market capitalisation of ₦93.8 billion, and the stock has returned 221.43% year-to-date. The nine-month result supports that re-rating on the income statement: profit is growing, and it is growing from core mortgage lending rather than one-off gains.
The questions sit on the other side of the balance sheet. Funding costs are rising faster than interest income, borrowings are growing much faster than deposits, and operations still consume cash. If the bank can keep loan growth funded without margins narrowing further, the earnings trajectory holds; if borrowing costs keep climbing at the current pace, they will eventually catch up with the top line.