Costs Ate the Revenue Growth
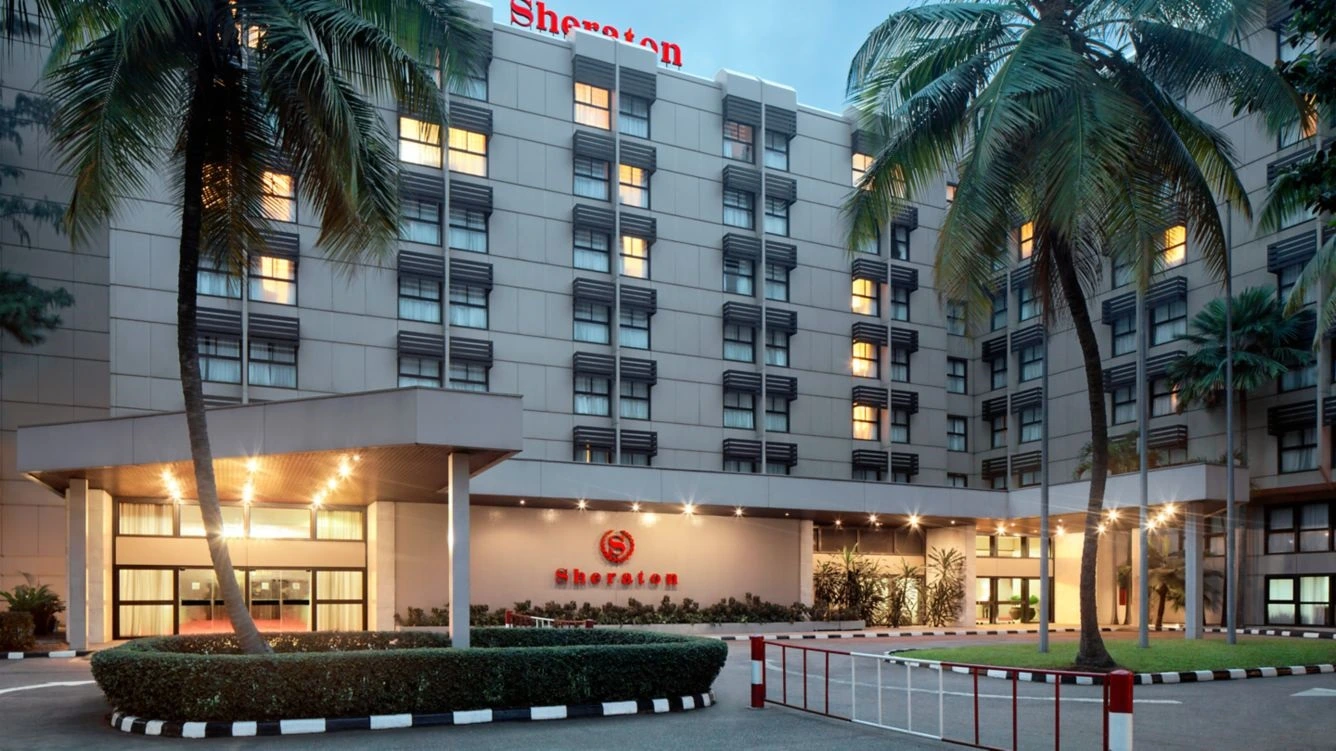
The owner of the Sheraton Lagos Hotel grew its top line only modestly in the nine months, and what growth it achieved did not survive the cost lines. Revenue of ₦19.41 billion was up 4.8%, but cost of sales rose 9.4% to ₦10.39 billion, and administrative and selling expenses also climbed, leaving gross profit broadly flat and pushing operating profit down 9.8% to ₦6.22 billion.
That pattern — rooms and food-and-beverage demand holding up, but inflation in operating costs moving faster — has defined the listed hotel sector through 2026, and Ikeja Hotel's nine months fit it closely.
Finance Income Did the Heavy Lifting
The bottom line improved anyway, because the group's earnings no longer depend only on hotel operations. Finance income — interest earned on its cash balances — rose 27% to ₦1.97 billion, and that inflow, rather than trading performance, lifted profit before tax by 15.1% to ₦8.19 billion and profit after tax to ₦5.31 billion.
The balance sheet behind that income is substantial: total assets of ₦80.96 billion and equity of ₦47.51 billion give the group a large cash-generating base relative to its hotel earnings, even though total assets were lower than a year earlier, in part because loans to related parties fell during the period.
What It Means for Investors
Ikeja Hotel's nine-month result is really two results. The hotel business itself earned less at the operating level than a year ago, squeezed by costs rising at roughly twice the pace of revenue. The investment and cash position, by contrast, delivered the profit growth shareholders will see in the headline.
For the shares to re-rate on fundamentals, investors will likely want the first of those stories to change: either revenue growth accelerating enough to cover cost inflation, or costs coming back under control. Until then, finance income remains the group's earnings cushion — valuable, but dependent on interest rates staying high enough to reward its cash pile.